Investment-linked insurance:What is investment-linked insurance and how does it differ from traditional life insurance?
Q: What is investment-linked insurance and how does it differ from traditional life insurance?
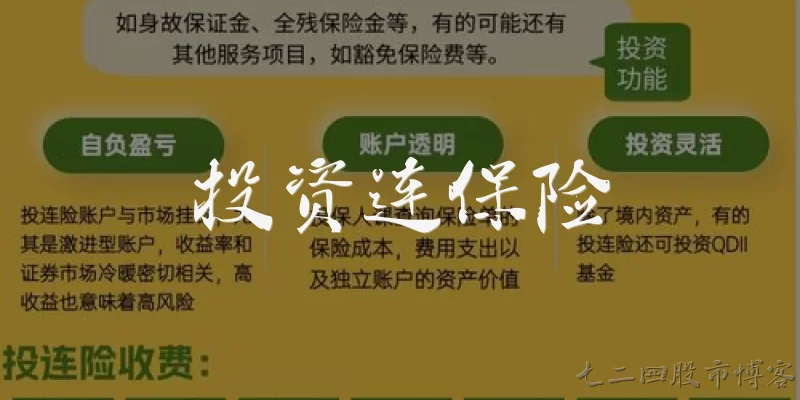
A: Investment-linked insurance (ILI) is a type of life insurance that combines protection with investment. Unlike traditional life insurance, where premiums are pooled and the insurer bears the investment risk, ILI allows policyholders to choose how their premiums are allocated among various investment funds. The policy's cash value and death benefit fluctuate based on the performance of these funds, so the policyholder bears the investment risk. Traditional policies typically offer guaranteed cash values and death benefits, while ILI offers no such guarantees. ILI provides greater transparency, as you can see exactly where your money is invested, but it also requires more active management and carries higher risks. It's suitable for those who want both insurance coverage and potential investment growth, and who are comfortable with market volatility.
Q: What are the main benefits and risks of investment-linked insurance policies?
A: The main benefits of investment-linked insurance (ILI) include potential for higher returns compared to traditional insurance, flexibility to switch between funds, and transparency of fees and fund performance. Policyholders can tailor their investment strategy to their risk tolerance and financial goals. Additionally, ILI often provides life insurance protection, so beneficiaries receive a payout if the insured dies. However, the risks are significant: investment returns are not guaranteed, and the cash value can decrease if the chosen funds perform poorly. There may be high surrender charges if you exit early, and the insurance charges can increase as you age, eroding your investment value. You also bear the risk of fund manager performance. Therefore, ILI is best for individuals with a long-term horizon who can tolerate market fluctuations and are willing to monitor their investments regularly.
Q: How should one choose the right investment-linked insurance plan?
A: Choosing the right investment-linked insurance (ILI) plan requires careful consideration of your financial goals, risk tolerance, and time horizon. First, assess your insurance needs: how much death benefit do you require? Then, evaluate the available funds—review their historical performance, fees, and investment objectives. Ensure the plan offers a range of funds that align with your risk appetite. Check the premium allocation rates, insurance charges, and surrender fees, as these can significantly impact returns. Compare different insurers' offerings, looking at fund management fees and flexibility to switch funds. Consider your ability to monitor and adjust investments regularly. It's also wise to consult a financial advisor who can help you understand the product's complexities. Remember, ILI is a long-term commitment, so choose a plan that fits your overall financial strategy and not just short-term market trends.
Q: What fees and charges are typically associated with investment-linked insurance?
A: Investment-linked insurance (ILI) policies come with various fees that can reduce your returns. Common charges include the premium allocation rate, which is the portion of each premium used to buy units in the investment funds; the difference goes to cover insurance costs and expenses. There is also a mortality and morbidity charge for the life insurance protection, which increases with age. Fund management fees are deducted from the fund's assets, typically ranging from 1% to 2% annually. Other possible fees include policy administration fees, surrender charges if you cash out early (often high in the first few years), and partial withdrawal fees. Some policies also have a bid-offer spread or switching fees for changing funds. It's crucial to read the product disclosure document to understand all charges, as they can significantly erode your investment value over time. Comparing fee structures across insurers can help you choose a cost-effective plan.
Words of experience
Common scenarios of "Investment-linked insurance"
【Customer】 Hi, I've been hearing a lot about investment-linked insurance lately. Can you explain what it is exactly?
【Agent】 Of course! Investment-linked insurance, often called ILP, is a type of life insurance that combines protection with investment. Part of your premium goes toward insurance coverage, and the rest is invested in funds of your choice.
【Customer】 So it's like buying insurance and investing at the same time? How does the money get split?
【Agent】 Exactly. The premium you pay is divided into two parts: one for the cost of insurance (like death benefit and other riders), and the other for investment in units of selected funds. The allocation depends on the plan and your age, among other factors.
【Customer】 What kind of funds can I invest in?
【Agent】 Typically, you can choose from a range of funds—equity funds, bond funds, balanced funds, money market funds, etc. The performance of these funds affects the cash value of your policy.
【Customer】 So the value can go up or down based on market performance? Is there any guarantee?
【Agent】 That's correct. The investment portion is subject to market risks, so the cash value is not guaranteed. However, some policies offer a minimum death benefit guarantee, but the investment returns are not guaranteed.
【Customer】 I see. What are the advantages compared to traditional whole life insurance?
【Agent】 ILPs offer potentially higher returns because you can invest in equity funds, and they provide flexibility—you can usually switch funds or adjust premiums. Traditional whole life insurance has fixed premiums and guaranteed cash values but lower growth potential.
【Customer】 That sounds appealing, but also riskier. What are the main risks I should be aware of?
【Agent】 Key risks include market risk (investment value can decline), liquidity risk (early surrender may result in significant losses), and insurance cost risk (charges may increase as you age, reducing investment value).
【Customer】 How are the insurance charges deducted? Are they fixed?
【Agent】 Insurance charges are typically deducted monthly from the policy's cash value by cancelling units. They are not fixed; they usually increase as you age because the cost of insurance rises. Other charges like fund management fees also apply.
【Customer】 So if the investment performs poorly, could the policy lapse?
【Agent】 Yes, if the cash value becomes insufficient to cover the insurance charges, the policy may lapse unless you pay additional premiums. That's why it's important to monitor performance and top up if needed.
【Customer】 Can I choose how much goes to insurance versus investment?
【Agent】 Some plans allow you to adjust the premium allocation, but usually the insurance charges are determined by the sum assured and your age. You can often choose a higher or lower sum assured, which affects the split.
【Customer】 What about surrender value? If I want to cash out early, what happens?
【Agent】 If you surrender early, you'll receive the cash value, which is the value of your investment units minus any surrender charges. In the early years, surrender charges can be high, so you might get back less than you paid.
【Customer】 Are there any tax benefits?
【Agent】 In some countries, investment gains within ILPs may be tax-deferred, and death benefits might be tax-free. But tax laws vary, so you should consult a tax advisor for your specific situation.
【Customer】 Who is this product suitable for?
【Agent】 It's suitable for individuals who want life insurance protection and are willing to accept investment risks for potentially higher returns. It's often used for long-term goals like retirement planning or wealth accumulation.
【Customer】 What if I'm risk-averse? Should I avoid ILPs?
【Agent】 If you're risk-averse, you might prefer traditional insurance with guaranteed returns. However, you could also choose a conservative fund within an ILP, but there's still some risk. It depends on your risk tolerance and financial goals.
【Customer】 How do I monitor the performance of my ILP?
【Agent】 You'll receive regular statements showing the value of your units and fund performance. You can also check online portals or contact your agent. It's important to review at least annually and adjust your investment strategy if needed.
【Customer】 Can I switch funds if I'm not happy with the performance?
【Agent】 Yes, most ILPs allow fund switching, sometimes a limited number of free switches per year, and a fee afterward. Switching can help you rebalance your portfolio according to market conditions.
【Customer】 What happens if I miss a premium payment?
【Agent】 If you miss a premium, there may be a grace period. After that, the policy might continue using the cash value to pay charges, but if the value is insufficient, it could lapse. Some policies offer automatic premium loans, but interest applies.
【Customer】 Are there any hidden fees I should watch out for?
【Agent】 Common fees include insurance charges, fund management fees, surrender charges, administrative fees, and sometimes premium allocation charges. Always read the product summary and fund factsheets to understand all fees.
【Customer】 Can you give me an example of how an ILP works over time?
【Agent】 Sure. Suppose you pay $500 monthly. $100 goes to insurance charges, $400 invested. If the fund grows 8% annually, after 20 years, the cash value could be substantial. But if the fund loses money, the value could be lower. Actual results vary.
【Customer】 That helps. What should I consider before buying an ILP?
【Agent】 Consider your financial goals, time horizon, risk tolerance, and whether you need life insurance. Compare different plans, understand the charges, and ensure you can afford the premiums long-term. Also, consult a financial advisor to tailor to your needs.