Asset Beta:What is asset beta and how does it differ from equity beta?
Q: What is asset beta and how does it differ from equity beta?
A: Asset beta, also known as unlevered beta, measures the risk of a firm's underlying assets independent of its capital structure. It reflects the business risk that arises from the firm's operations. Equity beta, or levered beta, includes both business risk and financial risk because it reflects the effect of debt on the firm's equity. According to a 2022 CFA Institute curriculum reading, asset beta is calculated by unlevering equity beta using the formula: Asset Beta = Equity Beta / [1 + (1 - Tax Rate) * (Debt/Equity)]. This distinction is crucial for comparing firms with different leverage.
Q: Why is asset beta important in corporate finance and valuation?
A: Asset beta isolates a firm's business risk from its financial risk, making it essential for cross-company comparisons and investment decisions. It is used to estimate the cost of capital for a project or division, especially when the project's risk differs from the firm's overall risk. A 2021 report by the CFA Institute emphasizes that asset beta helps in calculating the weighted average cost of capital (WACC) for firms with varying capital structures. Additionally, it aids in merger and acquisition analysis by providing a pure-play risk measure, as noted in a 2020 Journal of Applied Corporate Finance article.
Q: How do you calculate asset beta from equity beta?
A: Asset beta is derived from equity beta by removing the effects of financial leverage. The standard formula, as per the 2023 CFA Program Curriculum, is: Asset Beta = Equity Beta / [1 + (1 - Corporate Tax Rate) * (Total Debt / Total Equity)]. This adjustment accounts for the tax shield on debt. For example, if a firm has an equity beta of 1.2, a tax rate of 25%, and a debt-to-equity ratio of 0.5, the asset beta would be 1.2 / [1 + (0.75 * 0.5)] = 0.96. This calculation assumes debt beta is zero, which is common in practice.
Q: What are the limitations of using asset beta?
A: Asset beta assumes that debt is risk-free and that the firm's debt level remains constant, which may not hold in reality. It also assumes that the tax shield is certain and that operating risk is stable over time. According to a 2019 report by the Bank for International Settlements, these assumptions can distort risk estimates, especially for firms with high leverage or volatile earnings. Furthermore, asset beta does not capture changes in business risk due to market conditions. Therefore, analysts should use it with caution and complement it with other risk measures.
Q: How is asset beta used in estimating the cost of equity for a project?
A: Asset beta is used to estimate the cost of equity for a project by first re-levering it to reflect the project's target capital structure. The re-levered beta (equity beta) is then plugged into the Capital Asset Pricing Model (CAPM) to calculate the cost of equity. According to a 2020 article in the Journal of Corporate Finance, this approach, known as the pure-play method, is recommended by the CFA Institute for evaluating projects in different industries. For instance, if a firm enters a new sector, it can use the asset beta of comparable firms in that sector to derive a project-specific cost of equity.
Dialogue about
Common scenarios of "Asset Beta"
【Student】 Professor, I'm trying to understand the concept of asset beta. Could you explain what it is and why it's important?
【Professor】 Asset beta, also known as unlevered beta, measures the risk of a firm's assets without the impact of debt. It reflects the business risk of the company's operations. It's important because it allows us to compare the risk of companies with different capital structures.
【Student】 How is asset beta different from equity beta?
【Professor】 Equity beta reflects both business risk and financial risk, as it includes the effect of leverage. Asset beta removes the financial risk, showing only the business risk. The relationship is: Asset Beta = Equity Beta / (1 + (1 - Tax Rate) * (Debt/Equity)).
【Student】 So asset beta is always lower than equity beta for a levered firm?
【Professor】 Yes, for a levered firm, asset beta is lower than equity beta because debt increases the risk to equity holders. The formula shows that as debt increases, equity beta increases, but asset beta remains constant if the business risk doesn't change.
【Student】 Why would we use asset beta instead of equity beta in valuation?
【Professor】 When valuing a company or a project, we often use asset beta to calculate the cost of capital because it isolates the business risk. This is particularly useful when comparing companies with different leverage or when evaluating a project that will be financed differently than the firm's current capital structure.
【Student】 Can you give an example of how to calculate asset beta?
【Professor】 Sure. Suppose a company has an equity beta of 1.2, a debt-to-equity ratio of 0.5, and a tax rate of 30%. Then asset beta = 1.2 / (1 + (1 - 0.3) * 0.5) = 1.2 / (1 + 0.35) = 1.2 / 1.35 ≈ 0.89. So the asset beta is about 0.89.
【Student】 What does an asset beta of 0.89 mean in terms of risk?
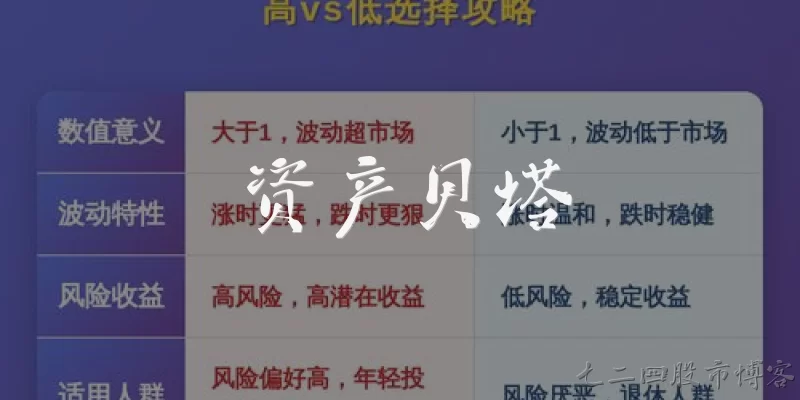
【Professor】 It means the firm's business risk is lower than the market average (since beta < 1). The assets are less volatile than the market. If the market return increases by 10%, the firm's asset value is expected to increase by about 8.9%, ignoring other factors.
【Student】 Is asset beta used in the CAPM?
【Professor】 Yes, in the context of the CAPM, we can use asset beta to estimate the required return on the firm's assets, which is the cost of capital for an all-equity financed firm. That is: Cost of Assets = Risk-Free Rate + Asset Beta * Market Risk Premium.
【Student】 How does asset beta change with leverage?
【Professor】 Asset beta should remain constant as leverage changes, assuming the business risk is unchanged. However, if the firm's operations change, asset beta would change. Leverage affects equity beta, not asset beta, according to the Hamada equation.
【Student】 What are the limitations of using asset beta?
【Professor】 Limitations include: it assumes debt is risk-free and perpetual, and that tax shields are certain. In reality, debt can be risky, and financial distress costs may affect the firm's risk. Also, estimating beta from historical data can be noisy.
【Student】 Can asset beta be negative?
【Professor】 Theoretically, beta can be negative if the asset's returns move inversely to the market. However, for most operating assets, betas are positive. Negative betas are rare and often associated with assets like gold or certain hedging instruments.
【Student】 How do we estimate asset beta for a private company?
【Professor】 We can use the asset beta of comparable public companies, adjust for differences in business risk, and then relever it to the private company's capital structure if needed. This is common in private equity valuations.
【Student】 Thank you, Professor. This has been very helpful.
【Professor】 You're welcome. Remember, asset beta is a key tool for understanding and comparing business risk across firms with different leverage.